The CONFOTUR law, read from a buyer's seat at Itza
CONFOTUR is the everyday name for Law 158-01, the Dominican statute that promotes tourism development, and for the council it set up to apply it. For a buyer it matters because an approved project's first purchasers can be exempt from the 3% property-transfer tax and from the 1% annual property tax, the IPI. At Itza Golden Residences those benefits are expected, not granted: the developer's own materials say the project is planned to carry them. This guide explains how a project moves through the law, what approval would mean for you, and what to verify before you rely on it.
What the law is, in one paragraph
Law 158-01 was enacted in 2001 to accelerate tourism development in regions of the country with the natural conditions for it. It created the Consejo de Fomento Turístico, the tourism promotion council whose Spanish initials give the law its everyday name, and it was amended in 2013 by Law 195-13, which set the annual property-tax exemption period at 15 years. The law's incentives attach to approved projects and the companies behind them. Buyers benefit as a consequence, and only in the specific ways the law and the tax authority describe, which is why the details below are worth reading slowly.
How a project earns CONFOTUR: provisional, then definitive
A project does not declare itself CONFOTUR. The council approves it through a classification, and its own site describes two kinds: provisional and definitive. Either one is the council's approval of a particular project as eligible for the law's incentives. Applications are filed by the developer through the Ministry of Tourism's online service, and the council's technical staff evaluate them before the council decides.
The two stages ask for different things. The provisional file is built around the project as designed: an application to the Minister of Tourism, a description of the project with images, the preliminary architectural plans, the land title or an option to buy it, and a pre-feasibility study. The definitive file adds the permissions a project gathers as it matures, including a current environmental authorisation from the Ministry of Environment and a full economic and financial feasibility analysis prepared to the Ministry of Finance's cost-benefit requirements, and it cites the provisional resolution where one was issued.
That is what lies behind a word like expected. A project can be designed with the law in mind, can hold a provisional classification, or can hold a definitive one, and each is a different level of certainty for the buyer.
-
Project designed The developer plans a project it believes fits the law. Nothing has been approved yet.
-
Provisional classification The council approves the project as designed, on the strength of plans, land rights and a pre-feasibility study.
-
Definitive classification The council approves it again with an environmental authorisation and a full feasibility and cost-benefit analysis in the file.
-
Buyer's exemption recorded For a qualifying first buyer, the exemption is filed and recorded against the title. It is not automatic.
Where Itza stands: expected, and what that word covers
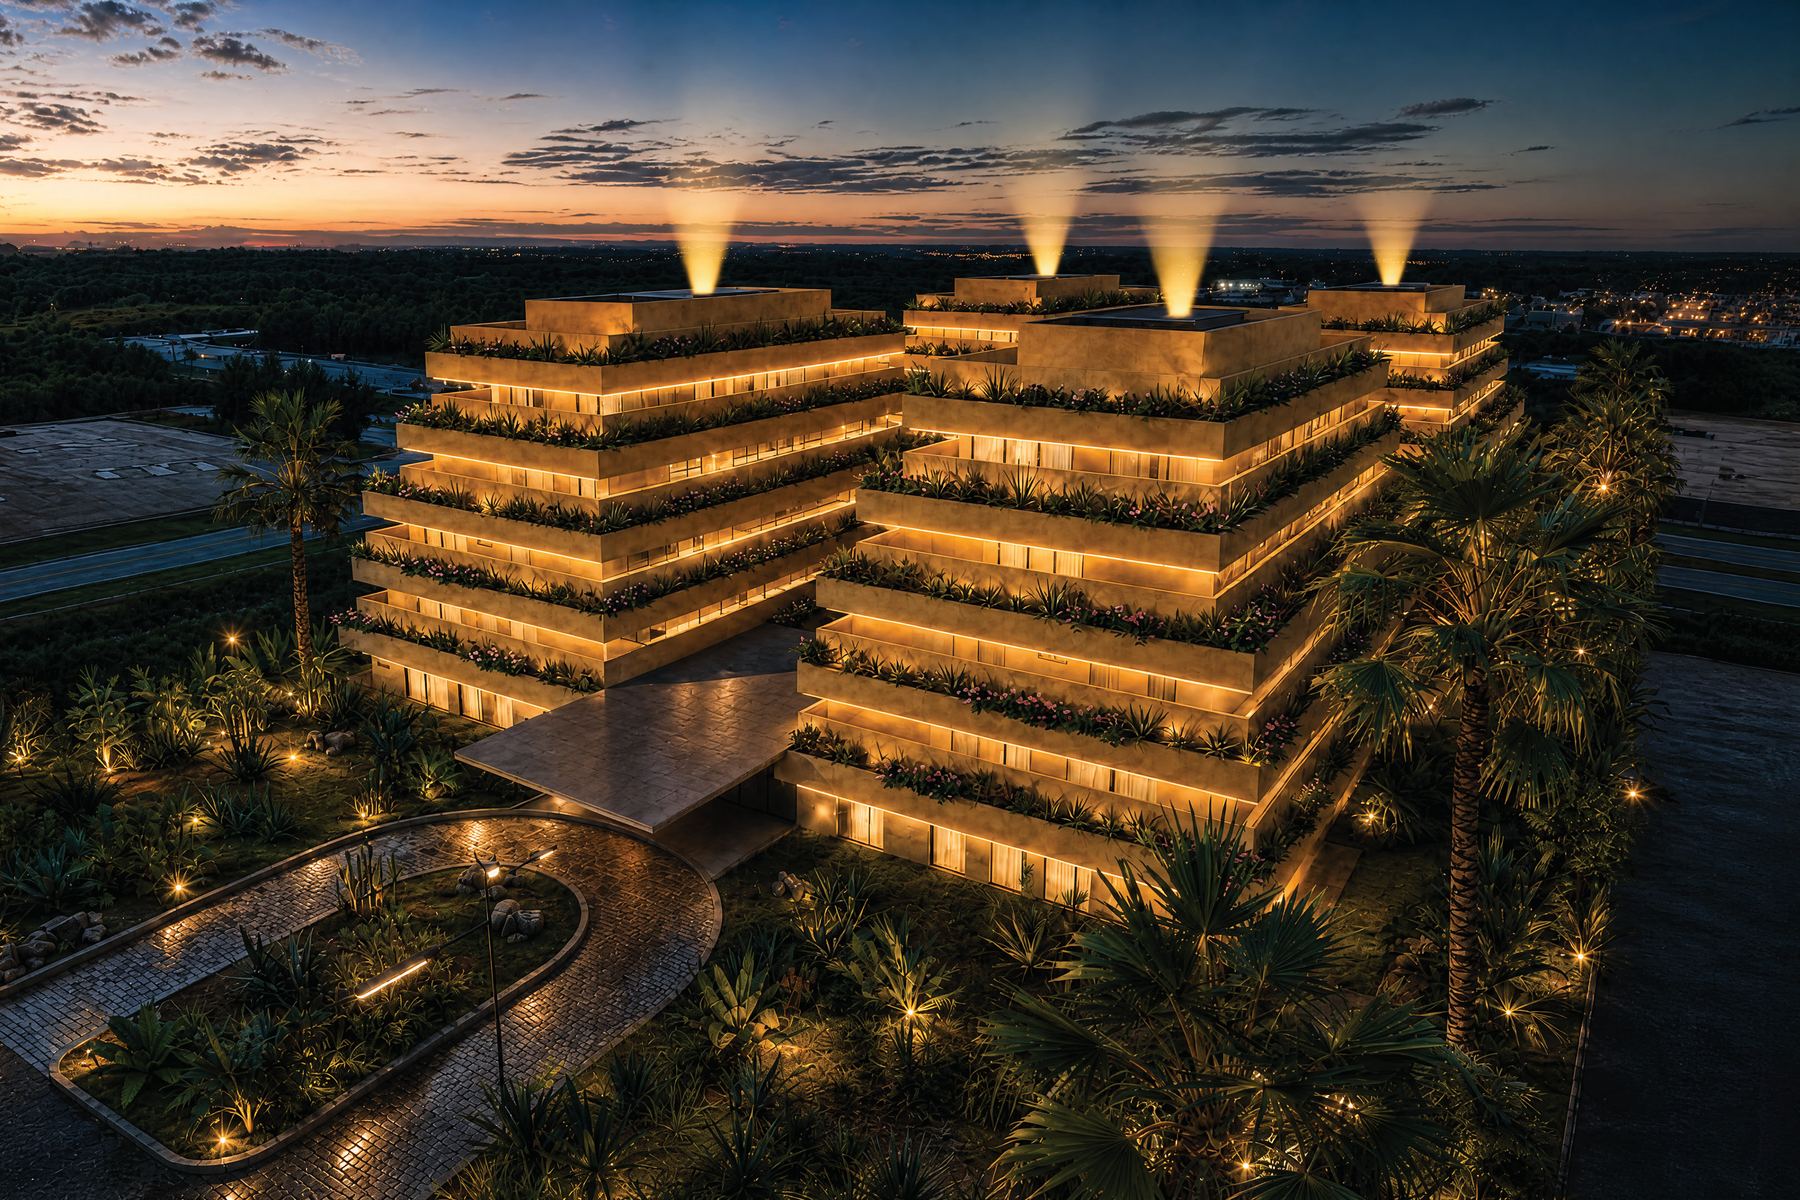
The developer's frequently asked questions state that Itza is expected to carry CONFOTUR benefits. That is a plan, not an approval, and this site does not publish a classification resolution number or date for the project. So the honest reading today is that Itza, a 52-residence project in four towers of 5 levels planned for delivery in Q4 2029, has been conceived to qualify, and that the classification itself remains to be confirmed.
This is a normal position for a project at this stage, and it is also exactly the point your attorney should pin down. Ask which classification the project holds, if any, and for the resolution number and date. Ask what the purchase contract says if a classification is not obtained. And ask when the exemption would be filed against your title, given that the title itself is registered after delivery.
What approval would mean for a first buyer
If the project obtains its classification, the law's benefits for buyers reach two taxes. The first is the 3% transfer tax normally charged on a property's registered value at closing; the initial purchasers of an approved project are exempt from it. The second is the IPI, the annual property tax of 1%, which for a property held personally is charged only on the part of its value above an exempt threshold that the tax authority adjusts every year.
Three conditions travel with those benefits. They are for first buyers from the developer only; a later resale does not pass them to the next owner, under Article 4 of the law. They are not automatic and must be filed and recorded on the title. And the 15-year period in Article 7 is written for the project and runs from the completion of construction, not from your closing date. How that period applies to a particular residence and owner is a question for your attorney, not a figure to pencil into a plan.
| Tax | Normal treatment | With an approved classification |
|---|---|---|
| Transfer tax at closing | 3% of registered value | Initial purchasers exempt |
| IPI, annual property tax | 1% on value above an annual threshold | Exempt; the law's 15-year period runs from completion of construction |
| Tax on rental income | Separate rules | Not changed by CONFOTUR |
| Resale to a later buyer | Transfer tax applies | Exemption does not pass on |
Where the status shows up in the numbers
The developer's investment projection for Itza shows 8.2% net on a two-bedroom model at an assumed 65% occupancy and a $276 average nightly rate, rising to about 10% if the owner's own 28 nights are valued as income. It is a projection, not a guarantee, and one of its assumptions is CONFOTUR itself: the model carries no annual property tax because it assumes the exemption. If the classification were not obtained, the IPI would apply to the value above the threshold and the projected return would be lower than shown.
Rental taxes sit outside the law altogether. Short-term tourist stays are subject to ITBIS at 18%, which the host rather than the booking platform is liable for, and a non-resident owner's rental income is subject to a 27% withholding on gross income. CONFOTUR exempts property taxes; how rental income is taxed in your case is a question for a tax adviser.
Questions to put to your attorney before you sign
None of this needs to be taken on trust, because the law works through documents. A Dominican real estate attorney acting for you can confirm the project's classification status from the council's resolution, read the contract's treatment of the tax, and see the exemption recorded on the title when it is issued. The list below keeps those checks in the order they fall in an off-plan purchase. The initial reservation at Itza is $5,000, which is a sensible moment to have these questions asked rather than after the contract.
-
Status Which classification does the project hold today, provisional, definitive or none, and what are the resolution number and date?
-
Contract How does the purchase contract treat the transfer tax, and what happens if a classification is not obtained?
-
Title When will title be registered in your name after delivery, and who files the exemption against it?
-
Projection Rerun any return projection with the IPI included, so you know the figure without the exemption as well as with it.
Common questions
- Is Itza CONFOTUR approved?
- Itza is expected to carry CONFOTUR benefits, according to the developer, but this site does not publish a classification resolution for the project. Treat the benefits as planned and ask your attorney to confirm the project's classification, and its resolution number and date, before relying on them.
- Which taxes does the CONFOTUR law exempt for a buyer?
- For the first buyers of an approved project, the 3% transfer tax at closing and the annual 1% property tax, the IPI, which is normally charged on value above an exempt threshold. Rental income is taxed under its own separate rules.
- Do I have to be a Dominican resident to benefit?
- No. The benefits attach to an approved project and its first buyers from the developer, and a foreign national can buy and hold Dominican property in their own name on the same terms as a Dominican.
- Does the exemption carry over if I sell?
- No. Article 4 of Law 158-01 limits the benefits to first buyers from the developer; a later buyer in a resale does not inherit them.
Want the details for your own situation?
Ask about availability, layouts or the buying process, and someone from the sales team will get back to you.
Get in touch